Beyond the Badge: How to Check Insurance Before Booking Home or Office Support
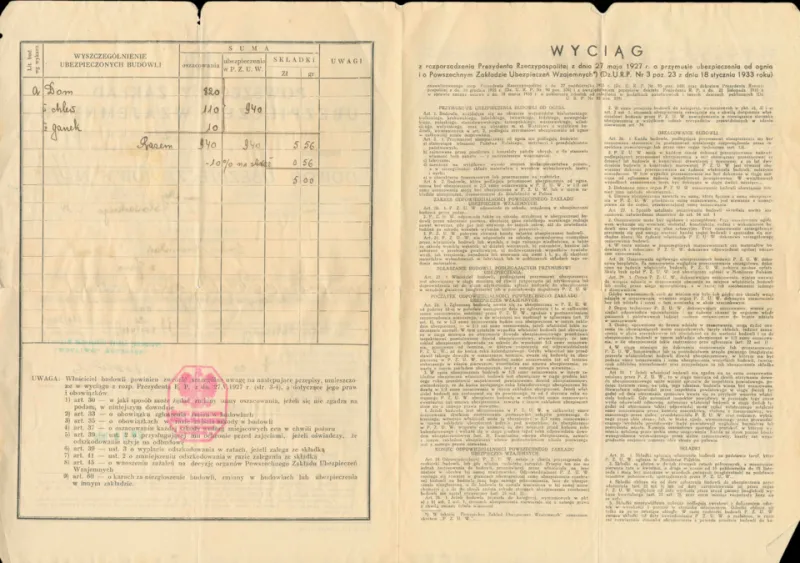
Photo: Powszechny Zakład Ubezpieczeń Wzajemnych, district inspector in Mołodeczno (issuing authority); individual form designer and signatory unidentified., Public domain, via Wikimedia Commons
If you have ever booked a cleaner, a handyperson, a gardener or a small office support team, you have probably heard the phrase ‘fully insured’. It is meant to put your mind at rest, and often it is genuinely true. But the phrase itself does not tell you what is covered, who is covered, or whether the paperwork is still in date.
That is not a reason to become suspicious of everyone. It is a reason to ask a few calm, practical questions before work begins. Whether you are a householder booking a one-off visit or a small business arranging regular support, a short document check can save a lot of confusion later.
The phrase is a starting point, not a certificate
‘Fully insured’ has no single legal definition. It usually means the business holds some combination of public liability, employer’s liability, and possibly professional indemnity or motor insurance. But the detail matters. A policy can be active, in date, and still exclude the exact work you are booking.
Think of the phrase as a signpost, not the destination. The useful question is not ‘are you fully insured?’ but ‘what cover do you hold for this work, and can I see the certificate?’
Public liability: the cover most people mean
Public liability insurance covers claims from third parties for injury or property damage linked to the business’s work. If a cleaner knocks over a lamp, or a contractor damages a floor while moving equipment, public liability is usually the relevant cover.
It is not generally a legal requirement for most trades and service businesses in the UK, but many responsible firms carry it. Limits vary. You might see £1 million, £2 million, £5 million or more. Higher is not automatically better if the policy excludes the work you need, but it is a useful starting point.
Ask whether the cover applies to work at your property, and whether it covers the specific tasks being booked. A general cleaning policy may not cover window cleaning at height, for example.
Employer’s liability: the one with a legal minimum
Employer’s liability insurance covers claims from employees who are injured or become ill because of their work. In Great Britain, most employers must hold at least £5 million of employer’s liability cover, and the certificate should be available. The rules differ slightly in Northern Ireland, so it is worth checking locally if that applies to you.
This matters when the person arriving at your home or office is an employee rather than a self-employed sole trader. If the business sends staff, it should be able to show employer’s liability cover. If it uses subcontractors, ask how those subcontractors are insured and whether the main business checks their cover.
Other covers that may matter
Public and employer’s liability are the big two for most home and office support, but they are not the only ones. Professional indemnity can matter if someone is giving advice rather than doing practical work. Motor insurance matters if a vehicle is used for the job. Contents or works insurance may matter for larger projects.
You do not need to become an insurance expert. You do need to know which cover is relevant to the job in front of you.
The documents worth asking for
A certificate of insurance is usually a one-page summary. A policy schedule gives more detail. Between them, look for:
- The insured business name, which should match the name on your quote or booking.
- The policy type, such as public liability or employer’s liability.
- The policy number and the insurance provider.
- The start and end dates, to confirm the cover is current.
- The limits of cover.
- Any excess, which is the amount the business may have to pay towards a claim.
- Key exclusions, or a summary of what is not covered.
If the trading name differs from the insured name, ask why. It may be perfectly normal, for example if the business trades under a brand name. But you want the link explained.
How to ask without it sounding like an accusation
Tone helps. You are not accusing anyone of anything. You are doing the same sort of check you would do before booking a venue or signing a lease.
Try a straightforward line: ‘Before we confirm, could you send over your public liability and employer’s liability certificates? It is a standard check on our side.’
If you are a small business, you can add: ‘Our insurer asks us to keep copies for contractors.’ If you are a householder, ‘I am just keeping a record for the property file’ is perfectly reasonable.
A professional business will not mind. A vague answer is not proof of a problem, but it is a reason to ask again or look elsewhere.
A five-minute check at the kitchen table
When the certificate arrives, do a quick scan rather than a deep audit.
- Check the business name against the quote.
- Check the policy dates cover the work dates.
- Check the limit is sensible for the job.
- Look for the word ‘exclusion’ and read the main ones.
- Confirm whether the people attending are employees or subcontractors.
- Save a copy with your booking notes.
If something does not add up, ask one clear question. ‘The certificate is in a different name to the quote — can you explain how they relate?’ is enough.
Quiet warnings
Most support businesses are honest and well run. Still, a few phrases are worth noticing. ‘We are fully insured, don’t worry about the paperwork’ is less helpful than a certificate. An expired date is not necessarily a disaster, but it needs explaining before work starts. A business that cannot say whether its staff are employees or subcontractors may not have a clear picture of its own cover.
None of these are automatic deal-breakers. They are simply prompts to slow down and ask.
If something goes wrong
If damage or injury happens, record what you can: photos, dates, names, and messages. Tell the business promptly and ask for its insurer details and claims process. Keep your own home or business insurer informed if the damage is significant. Do not wait months to raise it.
The reassuring part
Checking insurance is not about expecting the worst. It is about confirming that the practical arrangements match the friendly reassurance. A good support business should be able to answer these questions clearly, because it has done the work to be ready.
In 2026, ‘fully insured’ is still a useful phrase. Just treat it as the start of the conversation, not the end of it.